CIBIL score is an important metric for your financial health and maintaining a credit score of 700 and above is crucial to avail financial products with better terms and conditions.
You can check your CIBIL score for free on cibil.com once a year. As per RBI rules, TransUnion CIBIL gives every individual one free full credit report along with their credit history and credit score, each calendar year. Some banks and partner apps also provide your CIBIL score at no cost. Checking your own score is considered a soft inquiry and has no impact on your score.
Most people look up their CIBIL score for one of two reasons. A loan or credit card application is coming up, or one has just been turned down. Either way, you want the number quickly, and you want the right one. This article covers ways to check your CIBIL score, what to keep handy, what to do when the OTP refuses to arrive, and how to read your credit report.
Method 1: Check on the official TransUnion CIBIL website
The most convenient way to check your CIBIL score for free is through the CIBIL website, however, it comes with a caveat, you can check your score through official CIBIL Transunion website only once per calendar year, if you wish to check it again, you will be required to take their paid subscription.
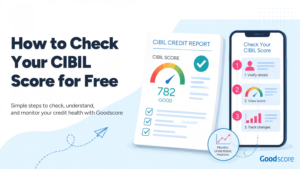
However, to check your once a year free credit score through CIBIL, follow the below mentioned steps:
- Go to cibil.com and choose the option for your free CIBIL Score and Report.
- Create an account with your name, email address and a password, and select PAN as your ID type.
- Enter your date of birth, PIN code and mobile number.
- Verify your identity. CIBIL sends an OTP to your mobile or email, and may also ask a few questions about your existing loans or cards.
- You’ll be shown paid plans along the way. You can skip these and continue with the free report.
- Your score and report open on your myCIBIL dashboard. Download the PDF and keep a copy.
If you already have an active myCIBIL account, all you have to do is to log in your CIBIL account, open My Account and click Get your Free Report. If that link is missing, you have probably already used this year’s free report, or you have an active paid plan.
The free report resets every calendar year, and not 12 months from your last check. CIBIL states that if you claimed it on or after 1 January 2026, your next free report is available from 1 January 2027.
What to keep ready when checking your CIBIL score
- PAN card
- The mobile number linked to your loans or credit cards
- An email address you can access right away
- Your date of birth, exactly as it appears on your PAN
- Your current address with PIN code
If identity verification or OTP fails
Nine times out of ten, a failed verification comes down to a mismatch between what you typed and what your lenders have on record.
The mobile number isn’t linked: If the number you entered isn’t the one your bank or card issuer has, the check can fail. Try the alternate verification route if one is offered, or update your number with the lender first. Keep in mind that the change reaches the bureau only after the lender’s next reporting cycle.
Your name or date of birth doesn’t match PAN: “Rahul K Sharma” and “Rahul Kumar Sharma” can look like two different people to the system. Enter your name and date of birth exactly as they appear on your PAN card.
Answers to identity questions don’t match: Answer from your actual records, such as a loan statement or card bill, rather than guessing.
In some cases, CIBIL may ask you to upload KYC documents through its KYC upload page, or you can reach its support team through the contact options on cibil.com to troubleshoot login related issues.
Method 2: Check through third party Apps
Many banks, lenders and fintech apps show a free credit score through tie-ups with credit bureaus. They are convenient, especially if you want to check more than once a year. Before you share your details, check three things:
If you wish to check your credit score multiple times during a year, then using third party apps is the most reliable option. Goodscore app allows you to check your score multiple times from three bureaus, namely, CIBIL, Experian and CRIF Highmark.
The Goodscore app will not only let you keep a track of your credit score from multiple bureaus, but also lets you see what has changed in your credit report and why. However, you will be charged a nominal fee to check your score across bureaus and also track your credit history, credit utilization, number of accounts, new enquiries and more to help you keep a better track of your financial activity.
GoodScore also offers paid AI assisted credit improvement service, which is designed to help improve your credit score and find the best available loan offers based on your financial profile.
Free vs paid CIBIL checks: what is the difference?
A free CIBIL report and GoodScore’s paid service offer different solutions. The free report is a snapshot, and it shows exactly where you stand with TransUnion CIBIL on the day you pull it.
Whereas, the GoodScore platform is about what happens next: tracking how your credit changes over time and working out a solution to fix it.
Many people check their CIBIL score once, see a number they don’t like, and don’t know what to do with it. That’s usually the point where a snapshot stops being enough.
| Features | Free annual CIBIL report | GoodScore credit builder (paid) |
|---|---|---|
| Bureau | TransUnion CIBIL | CIBIL, Experian and CRIF High Mark |
| How often | Once per calendar year | Daily tracking of score and report |
| What you get | Full CIBIL score and report | Detailed report, plus a breakdown of what is pulling your score down |
| Guidance | None; you read the report yourself | Personalised video analysis and a step-by-step plan from GoodScore’s credit experts, with a monthly review of your progress |
| Disputes | Raise them directly on myCIBIL | Help understanding which entries to dispute; you raise the dispute with the bureau or lender yourself |
| Cost | Free | Paid; Download GoodScore app for current plans |
| Best for | A once-a-year health check, or before a big loan application | Rebuilding a low score, or getting ready for a loan in the coming months |
If you only need your CIBIL number before an application, the free annual report on cibil.com is all you need. If your score has slipped and you’re not sure why, daily tracking with someone explaining your report will get you further than a single snapshot.
What your CIBIL score means (300-900, NH, -1)
A CIBIL score ranges from 300 to 900. The closer you are to 900, the stronger your credit history looks to a lender. CIBIL itself describes a score above 750 as good. But, every lender sets its own cut-off, and your income and existing EMIs matter just as much. A high score helps your case, but it doesn’t guarantee approval.
Here is a complete breakdown of your Credit Score ranges and what they actually mean for your financial health.
| Score range | What it means |
| NA / NH or any two digit numeric code | Not enough credit history to calculate a score. This is not a negative mark; it usually means you have never had a loan or card, or have had no credit activity for a long time. |
| 300-549 | Poor. Usually reflects missed payments, defaults or settled accounts. Most lenders will decline, or offer only secured credit. |
| 550-649 | Fair. Some lenders may approve, often with higher interest rates, lower limits or stricter terms. |
| 650-749 | Good. Many lenders will consider your application, though the best rates usually go to high scores. |
| 750-900 | Excellent. CIBIL describes scores above 750 as good. You are in the strongest position for approval and better rates. |
A higher band improves your chances, but approval also depends on your income, existing EMIs and each lender’s own policy.
Does checking your CIBIL score reduce it?
No. When you check your own score, it counts as a soft enquiry, and soft enquiries are not used in calculating your score. CIBIL actually recommends checking your score at least once a month, to stay on top of your credit health and catch errors or fraud early.
A hard inquiry is different. That happens when a lender pulls your report because you applied for a loan or a card. Several hard inquiries in a short time can weigh on your score, which is why applying to five lenders in a week is a bad idea.
Why your CIBIL score may differ from other scores
Each bureau uses its own data and scoring model, and reports pulled on different dates can show different information, which is the main reason you may see different scores across CIBIL, Experian, CRIF High Mark or Equifax. A gap of a few points, or even more, is normal.
Found something wrong in your CIBIL report?
Errors in your credit report can be quite common if you are not keeping a track of it. Common examples are a closed loan still showing as active, a payment marked late that you made on time, or an account that isn’t yours.
- Log in to myCIBIL and raise a dispute against the specific account or detail. CIBIL marks that section as “Under Dispute” while it checks with the lender.
- Or take it up directly with the lender that reported the information.
- Keep proof ready, such as a closure letter, NOC or bank statement.
Under RBI’s compensation framework, your complaint must be resolved within 30 calendar days. If it isn’t, you are entitled to ₹100 for every day of delay after that.
FAQs
Yes. RBI requires every credit bureau to give individuals with a credit report, including the score, each calendar year. TransUnion CIBIL offers this on cibil.com. For more frequent checks, you can take a paid CIBIL plan or download the Goodscore app.
PAN is the main identifier, but you’ll also need your name, date of birth and a mobile number or email for OTP and identity checks. Be careful with any website that promises your score “with just your PAN” and skips verification. A genuine check always asks for your consent and confirms it’s really you.
As many times as you like. CIBIL’s free full report is available once a calendar year, and extra checks come through a paid subscription or partner apps. Every time you check your own score, it’s a soft enquiry, so checking often has no effect on the score itself.
No. Checking your own score is a soft enquiry and isn’t used in scoring. Your score is affected only by hard enquiries, which happen when a lender pulls your report because you have applied for credit.
CIBIL scores range from 300 to 900. CIBIL describes a score above 750 as good, and many lenders use a similar benchmark. Approval still depends on your income, existing EMIs and each lender’s own policy, so no score guarantees a yes.
It means there isn’t enough credit history to calculate a score. It isn’t a negative mark. You’ll often see it if you’ve never had a loan or credit card. Taking a first card or a small loan and repaying it on time is usually enough to start building a score within a few months.
The app may be showing a score from a different bureau, such as Experian, CRIF High Mark or Equifax, or a report pulled on a different date. Each bureau has its own data and scoring model, so small differences are normal.
Since 1 January 2025, lenders must report to bureaus every fortnight, as on the 15th and the last day of each month. They have seven days to send the data, and the bureau then has five days to load it. In practice, a payment usually shows within a few weeks, not days.
Usually because the mobile number isn’t the one linked to your credit accounts, or your name or date of birth doesn’t match your PAN records. Update your details with your lender, try the alternate verification route if offered, or contact CIBIL support. Entering details exactly as they appear on PAN solves most cases.
Raise a dispute on the myCIBIL portal or directly with the lender, and keep supporting documents ready. Under RBI’s framework, your complaint should be resolved within 30 days. If it takes longer, you are entitled to ₹100 for each day of delay.